Skip to content

What Has Waiting Ever Done for Us?

Why do we wait? We wait for the right time. We wait for things to get a little better. We wait until we feel completely certain. And sometimes waiting does make us feel better. Sometimes, looking back over a short period of time, we can even point to a small benefit and say, “See, waiting worked.” 

But I think there is a bigger question worth asking: What has waiting really done for us? Has it consistently put us in a better position, or has it sometimes cost us an opportunity we didn’t recognize until it was gone? 

I remember during the 2008-2009 financial crisis, I was watching Bank of America stock. I told myself I would buy it when it dropped below $2 a share. I waited. And waited. It never got there. I had identified an opportunity, but instead of acting on what was available, I focused on getting an even better opportunity. Looking back, had I bought when I originally wanted to, that investment could have funded my retirement completely. 

That’s the problem with waiting: we’re often measuring today’s opportunity against some hypothetical version of tomorrow that may never arrive. 

I see the same thing happening when people think about their home and the role their housing wealth could play in retirement. With a Reverse Mortgage, for example, an adjustable-rate option can provide access to a line of credit. And this is where the cost of waiting can be easy to overlook. People tend to focus on what they might gain by waiting – perhaps a better rate, a higher home value, or simply greater comfort with the decision – but they don’t always consider what they may be giving up during that same period. One of those things can be potential line-of-credit growth. 

I have a client I’ll speak about only in general terms who has been waiting for roughly three years. Based on the scenario we originally discussed and where that line of credit could potentially be today, that decision to wait may have meant giving up more than six figures of potential line-of-credit growth. That doesn’t mean everyone should act immediately. It means waiting has a cost too, and that cost deserves to be part of the conversation. 

Often underneath the waiting is fear. Fear of making the wrong decision. Fear of something we heard from a friend, read online, or experienced years ago. Fear deserves to be addressed, but it shouldn’t be allowed to make the decision for us. If I’ve done my job correctly, you should understand the information well enough that fear is no longer driving the conversation. And if you’re still afraid, then we’re not finished. We need to go back, identify exactly what that fear is based on, revisit the information, and make sure every question has been answered. The goal isn’t to convince you to do something today. The goal is to make sure that if you decide to wait, you’re waiting because the information supports that decision – not simply because waiting feels safer. Because sometimes the greatest risk isn’t making a decision.

Donald Battista, NMLS ID 2030959. Mutual of Omaha Mortgage, Inc. dba Mutual of Omaha Reverse Mortgage, NMLS ID 1025894. 3131 Camino Del Rio N 1100, San Diego, CA 92108. Arizona Mortgage Banker License 0926603. Florida Mortgage Lender Servicer License MLD1827. Louisiana Residential Mortgage Lending License 1025894. Oklahoma Mortgage Lender License ML012498. Texas Mortgage Banker Registration 1025894. These materials are not from HUD or FHA and the document was not approved by HUD, FHA or any Government Agency. Subject to credit approval. For licensing information, go to: www.nmlsconsumeraccess.org

Equal Housing Lender #4574443596

#307:  Using reverse mortgage income to reduce IRMAA

SHIFT THE INCOME SOURCE; INVITE “AUNT IRMAA” TO MOVE OUT

With each of you retired from long and successful careers in the world of business, you’ve been blessed to be able to enjoy a satisfying standard of living as a couple. Then, some five years ago, an inheritance you received proved more than sufficient to refurbish your home to make “aging in place in style” a reality. Meanwhile, your husband, by taking on some consulting work a couple of years ago, supplemented your income stream, allowing you both to continue postponing taking any withdrawals from any tax-deferred accounts.   

Much to your dismay, you realize (after reading endless online pieces on the subject and one tearful session with your tax advisor), 2027 might prove to be a “pay the piper” time for you from a tax standpoint. Not only must you (you are four years older than your husband, and have just turned 73) take your first (of course, taxable!) Required Minimum Distribution from your retirement account, you’ve just learned that your monthly premiums for Medicare are likely to triple in 2027. 

IRMAA, (Medicare Income-Related Monthly Adjustment Amount), is what you pay in addition to your Part B and Part D Medicare premiums. Since you’re a married couple filing jointly, you’re both going to be paying the surcharge. And, with 2025 having been such a great year for extra earnings, 2027 will be the year the Social Security Administration considers when calculating IRMAA. 

While there’s no avoiding taking RMD’s out of your own retirement accounts, your husband can continue deferring his Social Security benefits – and his Required Minimum Distributions.

Meanwhile, consider using your housing wealth as a “standby” income resource. With reverse mortgage proceeds classified as loan advances rather than as income, you will have a way to fund any needed or desired lifestyle needs without inviting “Aunt IRMAA” to be a permanent guest in your home!

https://mutualreverse.com/david-garrison

David Garrison, NMLS ID 1595194. Mutual of Omaha Mortgage, Inc. dba Mutual of Omaha Reverse Mortgage, NMLS ID 1025894. 3131 Camino Del Rio N 1100, San Diego, CA 92108. Indiana-DFI Mortgage Lending License 43321. Michigan 1st Mortgage Broker/Lender/Servicer Registrant FR0022702. These materials are not from HUD or FHA and the document was not approved by HUD, FHA or any Government Agency. Subject to credit approval. For licensing information, go to: www.nmlsconsumeraccess.org

Equal Housing Lender 

#306: Using a reverse mortgage to finance family travel

USING HOME TO MAKE AWAY-FROM-HOME MEMORIES ACROSS THE GENERATIONS

Still getting used to the retired life on which you embarked just three years ago, you’ve been discussing hosting periodic family vacations to include your two grown children, the grandkids, possibly even inviting both sets of in-laws. 

With both of you experienced in project management, this “making memories project” seems quite do-able in terms of making all the arrangements. You envision paying for everyone’s hotel, and excursions, plus footing the bill for one big welcome dinner for all. (Each family would have to cover the cost of their other meals.) 

You’ve begun to create a general budget plan for the first trip in early 2027 and are now in the process of discussing with your wealth advisor which investment accounts to tap for executing each stage of the five-day “event”. (Also to be discussed is taking out a home equity loan, then repaying that loan over the course of a year, then again tapping the equity for each yearly trip.)

You might consider tapping into your housing wealth in a different way, by applying for a HECM reverse mortgage. The big difference is that there will never be any required monthly mortgage payments,* affording you much greater flexibility in terms of timing your withdrawals as the plans for the family trip progress. Meanwhile, any unused portion of your equity will be credited with growth at the same rate as that being charged on the borrowed funds. 

As Travel Weekly by Northstar presents the concept, “Multi-generational family travel brings grandparents, parents, and children together to share new experiences, build core memories, and bridge generational gaps,”  

Sounds as if the two of you are on the bandwagon, using your home equity to make away-from-home memories to share with your young and young-at-heart family members.

*Borrower must occupy home as primary residence and remain current on property taxes, homeowner’s insurance, the costs of home maintenance, and any HOA fees. David Garrison, NMLS ID 1595194. Mutual of Omaha Mortgage, Inc. dba Mutual of Omaha Reverse Mortgage, NMLS ID 1025894. 3131 Camino Del Rio N 1100, San Diego, CA 92108. Indiana-DFI Mortgage Lending License 43321. Michigan 1st Mortgage Broker/Lender/Servicer Registrant FR0022702. These materials are not from HUD or FHA and the document was not approved by HUD, FHA or any Government Agency. Subject to credit approval. For licensing information, go to: www.nmlsconsumeraccess.orgEqual Housing Lender 

The Cash Buyer Mindset Needs an Upgrade After Age 62

For decades, paying cash for a home has been viewed as the ultimate financial achievement. It’s often seen as the safest, smartest way to enter retirement: eliminate debt, own your home outright, and enjoy peace of mind. Here’s my unpopular opinion: that mindset deserves a serious upgrade.

Once you approach retirement, especially after age 62, the goal shouldn’t simply be owning your home free and clear. The goal should be to maximize your financial flexibility. Tying hundreds of thousands, or even millions, of dollars into an illiquid asset may provide emotional comfort, but it can also limit the very freedom you’ve spent a lifetime working to achieve.

The traditional definitions of “good debt” and “bad debt” also need to evolve. During your working years, debt is often judged by the interest rate or the monthly payment. In retirement, the conversation shifts. The question becomes: Does this financial strategy improve my quality of life while protecting my long-term wealth? A lifestyle home loan allows homeowners age 62 and older to access a portion of their home equity without required monthly mortgage payments,* while they continue to live in and own their home, provided they continue to meet the loan obligations. Instead of tying up all of your cash in the purchase of a home, it allows you to preserve liquidity, maintain investment opportunities, and keep more cash available for healthcare, travel, family, or unexpected expenses. That’s not reckless borrowing. That’s strategic planning.

The future of the cash buyer mindset isn’t paying cash; it’s thinking like a financially empowered homeowner. As life expectancy increases and retirement lasts longer than ever before, access to liquidity may become more valuable than eliminating every dollar of debt. The wealthiest retirees aren’t always the ones with the least debt; they’re often the ones with the greatest flexibility. It’s time for a paradigm shift. After age 62, the smartest financial move may not be writing the biggest check at closing; it may be preserving your wealth, your options, and your lifestyle for the years ahead. We have a way to do this. All we need to do is accept that our thinking about retirement has to evolve.

If you’re approaching retirement or are already 62 or older, don’t make one of the biggest financial decisions of your life based on yesterday’s thinking. Before you write a check for your next home, explore all of your options. A simple conversation could show you a strategy that helps you buy the home you want while preserving more of your wealth for the retirement you’ve worked so hard to build.

*Borrower must occupy home as primary residence and remain current on property taxes, homeowner’s insurance, the costs of home maintenance, and any HOA fees. Donald Battista, NMLS ID 2030959. Mutual of Omaha Mortgage, Inc. dba Mutual of Omaha Reverse Mortgage, NMLS ID 1025894. 3131 Camino Del Rio N 1100, San Diego, CA 92108. Arizona Mortgage Banker License 0926603. Florida Mortgage Lender Servicer License MLD1827. Louisiana Residential Mortgage Lending License 1025894. Oklahoma Mortgage Lender License ML012498. Texas Mortgage Banker Registration 1025894. These materials are not from HUD or FHA and the document was not approved by HUD, FHA or any Government Agency. Subject to credit approval. For licensing information, go to: www.nmlsconsumeraccess.org Equal Housing Lender #4549852126

The Race Between Home Appreciation and a Reverse Mortgage Line of Credit: Which Grows Faster?

When homeowners think about building wealth, they usually think about one thing: home appreciation. It’s true—real estate has been one of the most reliable long-term investments in America.

But there’s another asset that often gets overlooked: a reverse mortgage line of credit.

What surprises many homeowners is that an unused Home Equity Conversion Mortgage (HECM) line of credit doesn’t stay the same size. It grows over time, creating additional borrowing capacity without requiring monthly mortgage payments.*

So how does that compare to the growth of home values?

Home Appreciation: The Traditional Wealth Builder

According to long-term national housing data, U.S. home values have averaged approximately 4% annual appreciation over time.

Imagine a home worth $600,000 today.

At a 4% annual appreciation rate:

  • After 5 years: about $730,000
  • After 10 years: about $888,000
  • After 15 years: about $1.08 million

That’s impressive growth and one of the reasons many retirees have accumulated substantial home equity.

The Hidden Advantage: A Growing Line of Credit

Here’s where many people are surprised.

With an adjustable-rate FHA HECM, any unused line of credit grows over time. Instead of staying fixed, your available borrowing power increases each month—even if your home’s value doesn’t.

Suppose you establish a $250,000 line of credit and never draw from it.

If the line grows at approximately 6% annually (growth depends on the loan’s applicable interest rate and mortgage insurance premium), the available credit could grow to roughly:

  • After 5 years: $335,000
  • After 10 years: $448,000
  • After 15 years: $598,000

Unlike a traditional HELOC, you’re not required to requalify based on income, employment, or credit simply because your available credit has increased.

Which Grows Faster?

Home Value

  • Starts at: $600,000
  • Grows at: 4% annually

Unused HECM Line of Credit

  • Starts at: $250,000
  • Grows based on the loan’s applicable growth rate

In many interest-rate environments, the line of credit may grow faster than national average home appreciation.

That doesn’t mean your home’s value is increasing faster or slower—it simply means your available borrowing power may expand at a different pace.

Why This Matters in Retirement

Many retirees never intend to use their line of credit immediately.

Instead, they establish it while they qualify and allow it to grow for future needs, such as:

  • Healthcare expenses
  • Home renovations
  • Long-term care planning
  • Helping family members
  • Creating an emergency reserve
  • Managing retirement income during market downturns

Having access to a larger line years later can provide flexibility when financial needs change.

The Bottom Line

Home appreciation helps grow your wealth.

A HECM line of credit has the potential to grow your available borrowing capacity.

They’re two different forms of growth—but together they can become powerful retirement planning tools.

Rather than choosing one or the other, many homeowners view a growing line of credit as a way to complement the wealth they’ve already built through decades of homeownership.

*An FHA Home Equity Conversion Mortgage (HECM) line of credit is available only with eligible adjustable-rate HECM loans. The available line of credit grows over time based on the loan’s applicable interest rate plus the annual mortgage insurance premium, as established under FHA program rules. Growth rates are not guaranteed and will vary over time. Home appreciation is not guaranteed, and the 4% figure represents a long-term national average rather than future performance. Borrowers remain responsible for paying property taxes, homeowner’s insurance, maintaining the home, and complying with all loan terms.

John’s Test

This is a test blog.


The Original Intent of the Reverse Mortgage — and Why It Still Matters Today

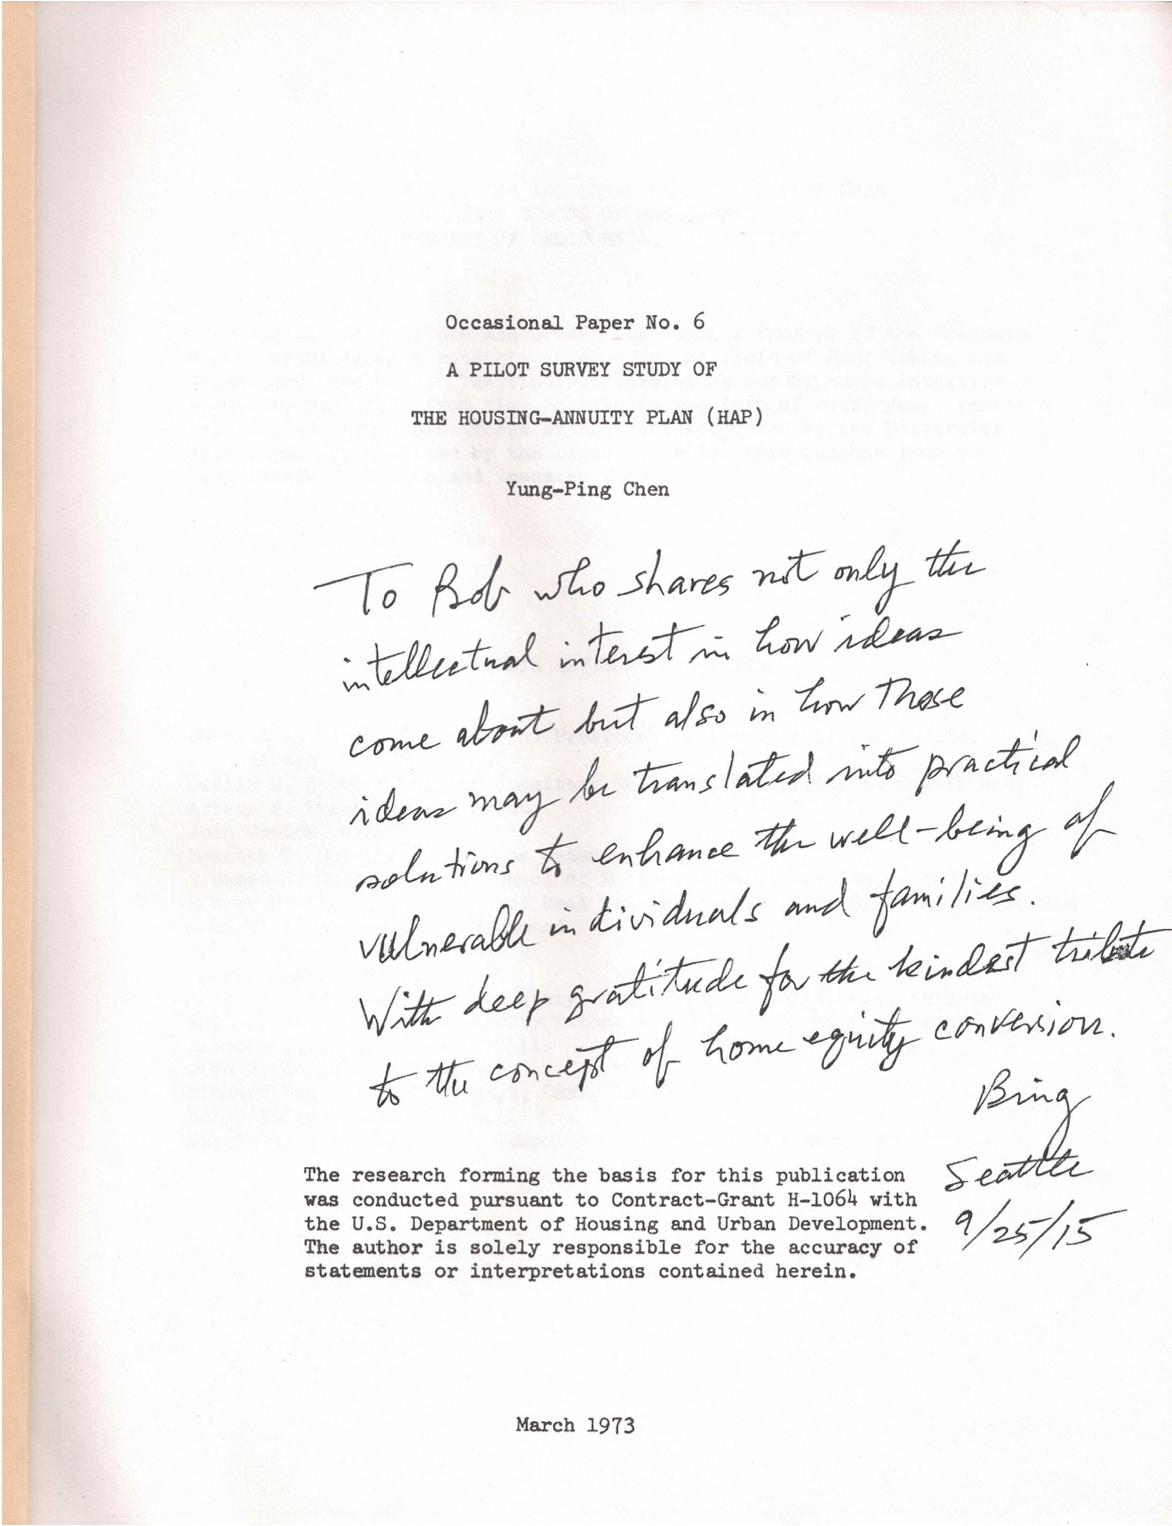
To really understand what the reverse mortgage was built for, you have to go back to the 1960s and a UCLA economist named Dr. Yung-Ping Chen. I had the chance to interview Dr. Chen a few years back, and what he told me about his original research reshaped how I think about home equity in retirement. He was generous enough to share a copy of his HUD-funded research with me — the study that carried his idea out of academic theory and into real public policy.

The Blind Spot in How We Measured Poverty

In the early 1960s, Dr. Chen was studying poverty among older Americans. Back then, poverty was measured almost entirely by cash flow: if a retiree’s Social Security check and pension fell under a certain line, they were labeled poor. Full stop.

Chen noticed a gap in that math.

A lot of older homeowners had thin monthly incomes but owned their homes outright, debt-free. On paper they looked broke. In reality, they were sitting on a substantial asset — they just had no way to turn it into usable cash without leaving the house.

Chen called this the “income poor but house rich” problem.

A Better Way to Define Wealth

His solution was to argue for a “net-worth approach” to financial well-being — one that counted assets, not just income.

If home equity could somehow be converted into spendable cash while the owner stayed put, Chen reasoned, a huge number of retirees would no longer look impoverished at all. Their wealth wasn’t gone; it was just frozen in the walls around them.

The obvious catch: selling the house to get at that equity defeated the whole purpose. People didn’t want to leave the homes where they’d raised families and built their lives.

That tension pushed Chen toward something new.

Born in a Senate Hearing: The Actuarial Mortgage Plan

In 1969, Chen brought his idea to Washington, testifying before the Senate Special Committee on Aging about what he called the Actuarial Mortgage Plan.

The goal, as he described it, was twofold: let older homeowners cash in the equity they’d spent decades building, and let them do it without having to move.

That hearing was the first real seed of what would eventually become the Home Equity Conversion Mortgage (HECM) — though it would take nearly two decades of work before Congress made it law.

It Was Never Just About the Loan

What stands out about Chen’s work is that he wasn’t thinking like a lender. He was making a philosophical argument: home equity is retirement wealth, full stop, and it shouldn’t be treated as separate from a person’s financial picture just because it’s illiquid.

His research pointed to something uncomfortable — a lot of “poor” retirees weren’t actually poor. Their biggest asset was simply invisible to the way we counted wealth. Give people a way to access that equity without selling, and you could improve their day-to-day finances while letting them stay exactly where they were.

From Idea to Law: A Twenty-Year Road

Getting from Chen’s testimony to an actual federal program took nearly twenty years. After his 1969 appearance before Congress, the idea moved through rounds of academic research, pilot programs, and policy debate. Economists, aging advocates, and housing groups kept refining the model, while lawmakers worked to balance retirement income needs against the risk of exploiting vulnerable homeowners.

That process finally landed with the Housing and Community Development Act of 1987, which created the HECM demonstration program. The first FHA-insured HECM closed in 1989 — a retirement tool two decades in the making, finally real.

The Original Idea Still Holds Up

Today, that original intent has been — and continues to be — the driving force behind the product. Most HECMs today are used to supplement older Americans’ retirement spending, letting them live more comfortably in the home they love.

The HECM has also grown well past its original use case. Today, financial planners use it in numerous ways. See my blog articleThe HECM Eight: Eight Powerful Ways a Reverse Mortgage Can Strengthen Your Retirement.

Every one of those strategies traces back to the same insight Chen had over sixty years ago: a home isn’t just shelter — for most retirees, it’s their single largest financial asset.

Used well, that equity can become a working part of a retirement income plan instead of sitting idle on paper. Chen’s core question from 1969 hasn’t gone anywhere: home equity clearly has value — so why should it stay off-limits just because it’s tied up in a house?

What Happens to a Reverse Mortgage When the Borrower Dies? A Complete Guide for Homeowners and Heirs

If you are considering a reverse mortgage, or helping a parent who already has one, you may be wondering what will happen to the home after the borrower passes away.

This is one of the most common concerns families have about reverse mortgages. It is also an area where there is a great deal of misinformation.

A reverse mortgage does not automatically transfer ownership of the home to the lender when the borrower dies. The home remains part of the borrower’s estate, and the heirs generally have several options for handling the property.

When Does the Reverse Mortgage Become Due?

A reverse mortgage generally becomes due and payable when the last surviving borrower dies or permanently leaves the home.

The loan may also become due if the borrower:

  • Sells the home
  • Moves out permanently
  • No longer uses the home as a primary residence
  • Fails to meet the loan obligations, including paying property taxes and homeowners insurance or maintaining the property

Different rules may apply when an eligible non-borrowing spouse remains in the home. Depending on the loan and whether certain requirements are met, that spouse may qualify to remain in the property after the borrowing spouse dies. Families in this situation should contact the loan servicer promptly to understand the available protections.

Does the Lender Automatically Take the Home?

No. A reverse mortgage is a loan secured by the home, just like a traditional mortgage. The lender has a lien on the property, but the homeowner retains the title.

After the borrower dies, the home is handled through the borrower’s estate. The heirs can decide whether they want to sell the property, keep it, or allow the lender to recover the property if there is no remaining equity.

The Heirs’ Options

Sell the home

Selling the property is the most common choice.

The reverse mortgage is paid from the sale proceeds, along with any applicable real estate expenses. If money remains after the loan and selling costs are paid, that equity belongs to the estate.

For example, suppose the home sells for $650,000 and the reverse mortgage balance is $390,000. After paying the loan balance and the costs associated with the sale, the remaining proceeds would go to the estate.

The amount of equity left will depend on the home’s value, the outstanding loan balance and the cost of selling the property.

Keep the home

An heir may choose to keep the property, but the reverse mortgage must first be satisfied.

This may be accomplished by:

  • Paying the balance with cash
  • Using other assets from the estate
  • Refinancing the balance into a traditional mortgage

With an FHA-insured Home Equity Conversion Mortgage, commonly called a HECM, special rules apply if the loan balance is higher than the home’s appraised value. In that situation, an heir who wants to keep the home may generally satisfy the debt by paying 95% of the appraised value rather than the full loan balance.

An heir who wants to keep the property should speak with the servicer early in the process. Refinancing and estate administration can take time.

Allow the lender to recover the property

A HECM is a nonrecourse loan. This means the lender generally looks to the property for repayment, not to the borrower’s heirs or their personal assets.

If the loan balance is greater than the home’s value and the family does not want to keep the property, the heirs may decide not to repay the loan. Depending on the circumstances, the estate may complete a deed in lieu of foreclosure or allow the lender to proceed with foreclosure.

The heirs generally are not personally responsible for paying the shortage between the home’s value and the loan balance.

How Much Time Do Heirs Have?

The loan servicer will provide the estate with information about the amount owed and the available options. The exact timeline may vary depending on the loan, the estate and what the heirs intend to do.

Extensions may be available when the heirs are actively working to sell the home or obtain financing, but they are not automatic. The estate may need to provide documentation showing that progress is being made.

For that reason, the heirs or the estate’s representative should contact the servicer as soon as possible after the borrower’s death. Waiting can limit the available options and make an already emotional process more difficult.

Will There Be Equity Left for the Heirs?

There may be. A reverse mortgage does not automatically consume all of the home’s equity.

The amount remaining for the estate depends on factors such as:

  • The home’s value when it is sold
  • The outstanding reverse mortgage balance
  • How much the borrower withdrew
  • How long the loan was in place
  • Interest and mortgage insurance charges added to the balance
  • Changes in the home’s value
  • Real estate and closing costs

Some homeowners use only part of their available reverse mortgage proceeds. Others may have the loan for many years. Because every situation is different, families should review the most recent loan statement and obtain a current estimate of the home’s value before making a decision.

Can a Borrower Lose the Home?

Having a reverse mortgage does not, by itself, cause the homeowner to lose the property. The borrower remains the owner and stays on the title.

However, the borrower must continue to meet the loan requirements. These typically include:

  • Occupying the home as a primary residence
  • Paying property taxes
  • Maintaining homeowners insurance
  • Keeping the property in reasonable condition
  • Paying applicable homeowners association fees

Failing to meet these obligations may cause the loan to become due and could eventually lead to foreclosure.

Planning Ahead Can Make the Process Easier

Families often do not discuss the reverse mortgage until the borrower has died or can no longer manage their finances. By that point, locating documents and deciding what to do with the home can feel overwhelming.

A few simple planning steps can make a meaningful difference:

  • Tell your family that you have a reverse mortgage.
  • Keep your loan documents and recent statements together.
  • Make sure a trusted family member knows the name of the loan servicer.
  • Discuss whether anyone may want to keep the home.
  • Keep property taxes, insurance and homeowners association payments current.
  • Review your estate plan with a qualified attorney.
  • Make sure the appropriate person has legal authority to communicate with the servicer when necessary.

These conversations may feel uncomfortable, but they can spare loved ones from having to make important decisions without enough information.

The Bottom Line

When a reverse mortgage borrower dies, the lender does not automatically become the owner of the home. The property remains part of the estate, and the heirs generally have the option to sell it, keep it by satisfying the loan, or allow the lender to recover it.

If equity remains after the reverse mortgage and selling expenses are paid, that equity belongs to the estate. If the loan balance exceeds the home’s value, the nonrecourse protection of an FHA-insured HECM generally prevents the borrower’s heirs from being personally responsible for the shortage.

The most important step is to communicate with the loan servicer promptly. Understanding the loan and discussing the family’s preferences in advance can make the process much easier when the time comes.

This article provides general information and is not legal, tax or financial advice. Loan requirements and estate laws may vary. Homeowners and heirs should consult the loan servicer and appropriate professional advisers regarding their circumstances.

What Are the Pros and Cons of Today’s Reverse Mortgage?

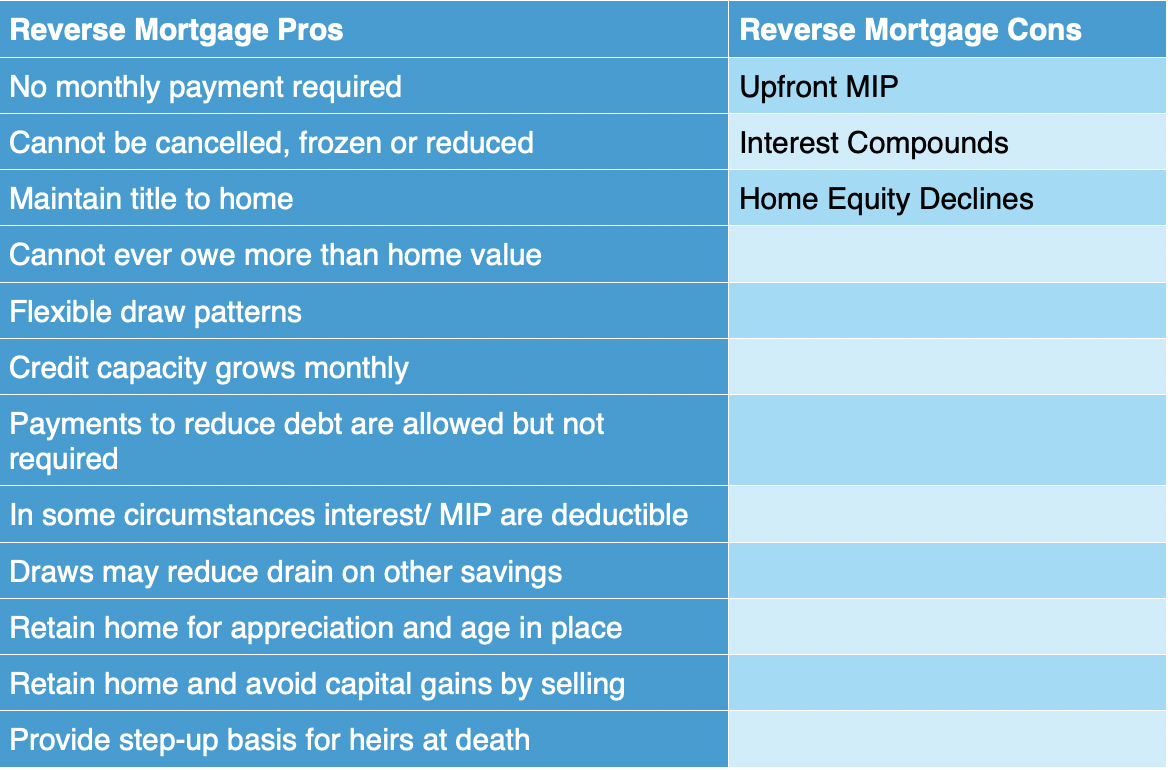
A reverse mortgage allows homeowners, typically aged 62 or older, to convert home equity into cash without selling their home or making monthly payments. Key pros include no obligatory mortgage payments, tax-free proceeds, optional flexible payment options, and protection against owing more than the home’s value. Main cons include significant upfront costs and increasing loan balance that can reduce home equity.

Key Pros:

  • No monthly mortgage payments: Borrowers can eliminate monthly payments, which can ease financial pressure and allow seniors to age in place.
  • Tax-free funds: Proceeds are generally not considered taxable income, and do not affect Social Security or Medicare benefits.
  • Flexible disbursement options: Borrowers can choose to receive funds as a lump sum, monthly payments, a line of credit, or a combination.
  • Non-recourse loan: Borrowers or heirs will never owe more than the home’s value when the loan is repaid, regardless of the loan balance.
  • Retain home ownership: Borrowers keep the title and can remain in their home, provided they fulfill obligations like property maintenance, taxes, and insurance.
  • Heirs have multiple options: When the homeowner leaves the home, heirs may repay the loan, sell the home and keep surplus equity, or, if the loan exceeds the home’s value, surrender the property with no further obligation.

Key Cons:

  • Accruing fees:  Reverse mortgages typically have higher closing costs, the most significant of which is the upfront FHA Mortgage Insurance Premium.
  • Decreasing home equity: If no payments are made, an absolute right of the homeowner, the loan balance grows over time, reducing the equity left for heirs or the homeowners if they sell and move.
  • Impact on inheritance: The growing loan balance can reduce the initial home value. 
  • Eligibility risks: As with all mortgages in the US, the homeowner must keep the home as their primary residence, maintain the property, and keep up with taxes and insurance.
  • Potential impact on means-tested benefits: While Social Security and Medicare are not affected, receiving large lump sums could impact eligibility for Medicaid or Supplemental Security Income (SSI). This subset of homeowners should take care to draw only what they need to spend for the month.

Clearly, the modern FHA-Insured reverse mortgage offers impressive benefits. The main drawbacks are related to cost, mostly the cost of insuring the loan. Many seniors find it reassuring that the loan is backed by the full faith and credit of the United States Government. Nevertheless, there are ways to reduce the overall cost of the reverse mortgage.

Key Methods for Reducing Overall Cost of Reverse Mortgages:

Payments on the reverse mortgage can be made or discontinued at any interval chosen by the homeowner

Paying the largest expense, the upfront MIP, instead of including it in the loan produces higher growth in available credit, and reduces the decline in home equity

Paying the largest expense, the upfront MIP as above, can result, for homeowners who itemize, in a tax reduction if the reverse mortgage is being used to purchase a new home or replace their purchase loan or to substantially renovate for a more desirable environment to age in place.

Making a large payment on an existing reverse mortgage in high-earning year to offset taxes

Taking draws from the reverse mortgage can be used in retirement planning :

Provide cash for living expenses while deferring Social Security

Meet irregular expenses such medical, aging home, or rising tax and insurance 

Self-insure for long-term care. Don’t use it, don’t owe it

Substitute reverse mortgage for portfolio draws in down markets, avoid buying high and selling low

Avoid paying capital gains by not selling to meet expenses

In high appreciation areas, retain the home for continued wealth building

Restrict capital gains for heirs by passing home on stepped-up basis

In senior divorce, equalize housing and reduce drain on marital cash

Over the last decade, there has been an explosion in retirement planning uses for reverse mortgages. Financial professionals appreciate how a usually dormant asset, the home, can be mobilized to work in concert with other assets.