Skip to content

The Cash Buyer Mindset Needs an Upgrade After Age 62

For decades, paying cash for a home has been viewed as the ultimate financial achievement. It’s often seen as the safest, smartest way to enter retirement: eliminate debt, own your home outright, and enjoy peace of mind. Here’s my unpopular opinion: that mindset deserves a serious upgrade.

Once you approach retirement, especially after age 62, the goal shouldn’t simply be owning your home free and clear. The goal should be to maximize your financial flexibility. Tying hundreds of thousands, or even millions, of dollars into an illiquid asset may provide emotional comfort, but it can also limit the very freedom you’ve spent a lifetime working to achieve.

The traditional definitions of “good debt” and “bad debt” also need to evolve. During your working years, debt is often judged by the interest rate or the monthly payment. In retirement, the conversation shifts. The question becomes: Does this financial strategy improve my quality of life while protecting my long-term wealth? A lifestyle home loan allows homeowners age 62 and older to access a portion of their home equity without required monthly mortgage payments,* while they continue to live in and own their home, provided they continue to meet the loan obligations. Instead of tying up all of your cash in the purchase of a home, it allows you to preserve liquidity, maintain investment opportunities, and keep more cash available for healthcare, travel, family, or unexpected expenses. That’s not reckless borrowing. That’s strategic planning.

The future of the cash buyer mindset isn’t paying cash; it’s thinking like a financially empowered homeowner. As life expectancy increases and retirement lasts longer than ever before, access to liquidity may become more valuable than eliminating every dollar of debt. The wealthiest retirees aren’t always the ones with the least debt; they’re often the ones with the greatest flexibility. It’s time for a paradigm shift. After age 62, the smartest financial move may not be writing the biggest check at closing; it may be preserving your wealth, your options, and your lifestyle for the years ahead. We have a way to do this. All we need to do is accept that our thinking about retirement has to evolve.

If you’re approaching retirement or are already 62 or older, don’t make one of the biggest financial decisions of your life based on yesterday’s thinking. Before you write a check for your next home, explore all of your options. A simple conversation could show you a strategy that helps you buy the home you want while preserving more of your wealth for the retirement you’ve worked so hard to build.

*Borrower must occupy home as primary residence and remain current on property taxes, homeowner’s insurance, the costs of home maintenance, and any HOA fees. Donald Battista, NMLS ID 2030959. Mutual of Omaha Mortgage, Inc. dba Mutual of Omaha Reverse Mortgage, NMLS ID 1025894. 3131 Camino Del Rio N 1100, San Diego, CA 92108. Arizona Mortgage Banker License 0926603. Florida Mortgage Lender Servicer License MLD1827. Louisiana Residential Mortgage Lending License 1025894. Oklahoma Mortgage Lender License ML012498. Texas Mortgage Banker Registration 1025894. These materials are not from HUD or FHA and the document was not approved by HUD, FHA or any Government Agency. Subject to credit approval. For licensing information, go to: www.nmlsconsumeraccess.org Equal Housing Lender #4549852126
The Race Between Home Appreciation and a Reverse Mortgage Line of Credit: Which Grows Faster?

When homeowners think about building wealth, they usually think about one thing: home appreciation. It’s true—real estate has been one of the most reliable long-term investments in America.

But there’s another asset that often gets overlooked: a reverse mortgage line of credit.

What surprises many homeowners is that an unused Home Equity Conversion Mortgage (HECM) line of credit doesn’t stay the same size. It grows over time, creating additional borrowing capacity without requiring monthly mortgage payments.*

So how does that compare to the growth of home values?

Home Appreciation: The Traditional Wealth Builder

According to long-term national housing data, U.S. home values have averaged approximately 4% annual appreciation over time.

Imagine a home worth $600,000 today.

At a 4% annual appreciation rate:

  • After 5 years: about $730,000
  • After 10 years: about $888,000
  • After 15 years: about $1.08 million

That’s impressive growth and one of the reasons many retirees have accumulated substantial home equity.

The Hidden Advantage: A Growing Line of Credit

Here’s where many people are surprised.

With an adjustable-rate FHA HECM, any unused line of credit grows over time. Instead of staying fixed, your available borrowing power increases each month—even if your home’s value doesn’t.

Suppose you establish a $250,000 line of credit and never draw from it.

If the line grows at approximately 6% annually (growth depends on the loan’s applicable interest rate and mortgage insurance premium), the available credit could grow to roughly:

  • After 5 years: $335,000
  • After 10 years: $448,000
  • After 15 years: $598,000

Unlike a traditional HELOC, you’re not required to requalify based on income, employment, or credit simply because your available credit has increased.

Which Grows Faster?

Home Value

  • Starts at: $600,000
  • Grows at: 4% annually

Unused HECM Line of Credit

  • Starts at: $250,000
  • Grows based on the loan’s applicable growth rate

In many interest-rate environments, the line of credit may grow faster than national average home appreciation.

That doesn’t mean your home’s value is increasing faster or slower—it simply means your available borrowing power may expand at a different pace.

Why This Matters in Retirement

Many retirees never intend to use their line of credit immediately.

Instead, they establish it while they qualify and allow it to grow for future needs, such as:

  • Healthcare expenses
  • Home renovations
  • Long-term care planning
  • Helping family members
  • Creating an emergency reserve
  • Managing retirement income during market downturns

Having access to a larger line years later can provide flexibility when financial needs change.

The Bottom Line

Home appreciation helps grow your wealth.

A HECM line of credit has the potential to grow your available borrowing capacity.

They’re two different forms of growth—but together they can become powerful retirement planning tools.

Rather than choosing one or the other, many homeowners view a growing line of credit as a way to complement the wealth they’ve already built through decades of homeownership.

*An FHA Home Equity Conversion Mortgage (HECM) line of credit is available only with eligible adjustable-rate HECM loans. The available line of credit grows over time based on the loan’s applicable interest rate plus the annual mortgage insurance premium, as established under FHA program rules. Growth rates are not guaranteed and will vary over time. Home appreciation is not guaranteed, and the 4% figure represents a long-term national average rather than future performance. Borrowers remain responsible for paying property taxes, homeowner’s insurance, maintaining the home, and complying with all loan terms.

John’s Test

This is a test blog.


The Original Intent of the Reverse Mortgage — and Why It Still Matters Today

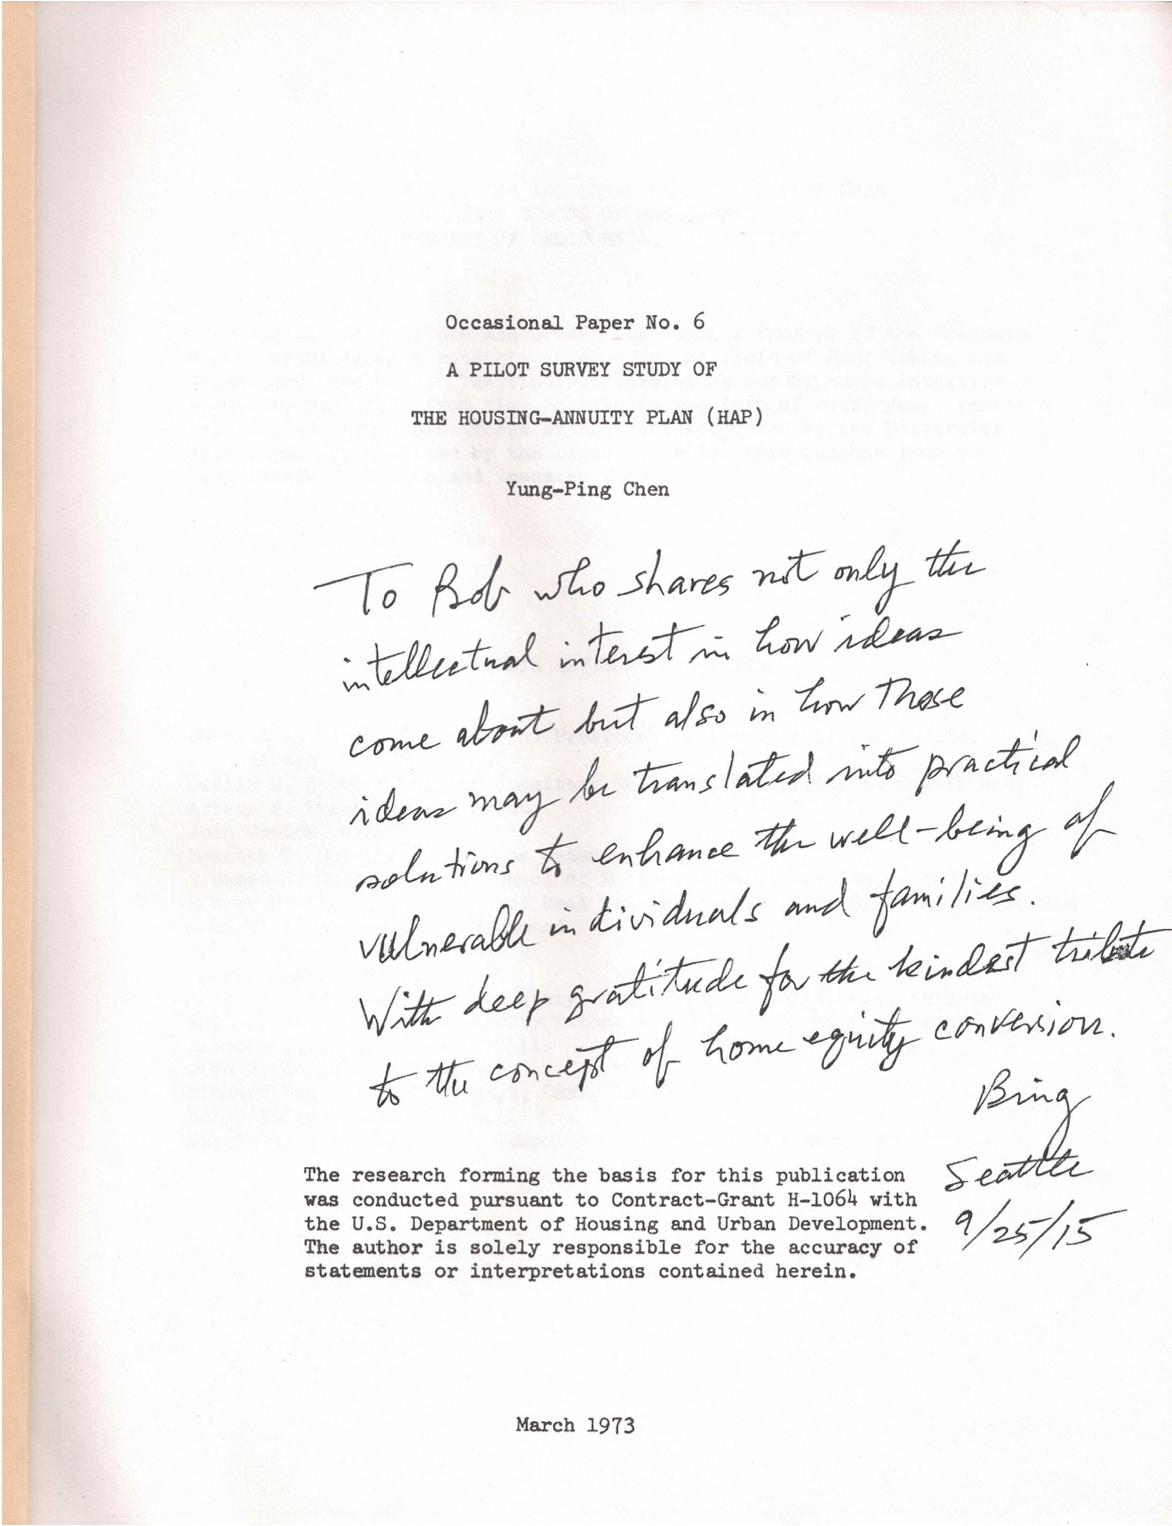
To really understand what the reverse mortgage was built for, you have to go back to the 1960s and a UCLA economist named Dr. Yung-Ping Chen. I had the chance to interview Dr. Chen a few years back, and what he told me about his original research reshaped how I think about home equity in retirement. He was generous enough to share a copy of his HUD-funded research with me — the study that carried his idea out of academic theory and into real public policy.

The Blind Spot in How We Measured Poverty

In the early 1960s, Dr. Chen was studying poverty among older Americans. Back then, poverty was measured almost entirely by cash flow: if a retiree’s Social Security check and pension fell under a certain line, they were labeled poor. Full stop.

Chen noticed a gap in that math.

A lot of older homeowners had thin monthly incomes but owned their homes outright, debt-free. On paper they looked broke. In reality, they were sitting on a substantial asset — they just had no way to turn it into usable cash without leaving the house.

Chen called this the “income poor but house rich” problem.

A Better Way to Define Wealth

His solution was to argue for a “net-worth approach” to financial well-being — one that counted assets, not just income.

If home equity could somehow be converted into spendable cash while the owner stayed put, Chen reasoned, a huge number of retirees would no longer look impoverished at all. Their wealth wasn’t gone; it was just frozen in the walls around them.

The obvious catch: selling the house to get at that equity defeated the whole purpose. People didn’t want to leave the homes where they’d raised families and built their lives.

That tension pushed Chen toward something new.

Born in a Senate Hearing: The Actuarial Mortgage Plan

In 1969, Chen brought his idea to Washington, testifying before the Senate Special Committee on Aging about what he called the Actuarial Mortgage Plan.

The goal, as he described it, was twofold: let older homeowners cash in the equity they’d spent decades building, and let them do it without having to move.

That hearing was the first real seed of what would eventually become the Home Equity Conversion Mortgage (HECM) — though it would take nearly two decades of work before Congress made it law.

It Was Never Just About the Loan

What stands out about Chen’s work is that he wasn’t thinking like a lender. He was making a philosophical argument: home equity is retirement wealth, full stop, and it shouldn’t be treated as separate from a person’s financial picture just because it’s illiquid.

His research pointed to something uncomfortable — a lot of “poor” retirees weren’t actually poor. Their biggest asset was simply invisible to the way we counted wealth. Give people a way to access that equity without selling, and you could improve their day-to-day finances while letting them stay exactly where they were.

From Idea to Law: A Twenty-Year Road

Getting from Chen’s testimony to an actual federal program took nearly twenty years. After his 1969 appearance before Congress, the idea moved through rounds of academic research, pilot programs, and policy debate. Economists, aging advocates, and housing groups kept refining the model, while lawmakers worked to balance retirement income needs against the risk of exploiting vulnerable homeowners.

That process finally landed with the Housing and Community Development Act of 1987, which created the HECM demonstration program. The first FHA-insured HECM closed in 1989 — a retirement tool two decades in the making, finally real.

The Original Idea Still Holds Up

Today, that original intent has been — and continues to be — the driving force behind the product. Most HECMs today are used to supplement older Americans’ retirement spending, letting them live more comfortably in the home they love.

The HECM has also grown well past its original use case. Today, financial planners use it in numerous ways. See my blog articleThe HECM Eight: Eight Powerful Ways a Reverse Mortgage Can Strengthen Your Retirement.

Every one of those strategies traces back to the same insight Chen had over sixty years ago: a home isn’t just shelter — for most retirees, it’s their single largest financial asset.

Used well, that equity can become a working part of a retirement income plan instead of sitting idle on paper. Chen’s core question from 1969 hasn’t gone anywhere: home equity clearly has value — so why should it stay off-limits just because it’s tied up in a house?

What Happens to a Reverse Mortgage When the Borrower Dies? A Complete Guide for Homeowners and Heirs

If you are considering a reverse mortgage, or helping a parent who already has one, you may be wondering what will happen to the home after the borrower passes away.

This is one of the most common concerns families have about reverse mortgages. It is also an area where there is a great deal of misinformation.

A reverse mortgage does not automatically transfer ownership of the home to the lender when the borrower dies. The home remains part of the borrower’s estate, and the heirs generally have several options for handling the property.

When Does the Reverse Mortgage Become Due?

A reverse mortgage generally becomes due and payable when the last surviving borrower dies or permanently leaves the home.

The loan may also become due if the borrower:

  • Sells the home
  • Moves out permanently
  • No longer uses the home as a primary residence
  • Fails to meet the loan obligations, including paying property taxes and homeowners insurance or maintaining the property

Different rules may apply when an eligible non-borrowing spouse remains in the home. Depending on the loan and whether certain requirements are met, that spouse may qualify to remain in the property after the borrowing spouse dies. Families in this situation should contact the loan servicer promptly to understand the available protections.

Does the Lender Automatically Take the Home?

No. A reverse mortgage is a loan secured by the home, just like a traditional mortgage. The lender has a lien on the property, but the homeowner retains the title.

After the borrower dies, the home is handled through the borrower’s estate. The heirs can decide whether they want to sell the property, keep it, or allow the lender to recover the property if there is no remaining equity.

The Heirs’ Options

Sell the home

Selling the property is the most common choice.

The reverse mortgage is paid from the sale proceeds, along with any applicable real estate expenses. If money remains after the loan and selling costs are paid, that equity belongs to the estate.

For example, suppose the home sells for $650,000 and the reverse mortgage balance is $390,000. After paying the loan balance and the costs associated with the sale, the remaining proceeds would go to the estate.

The amount of equity left will depend on the home’s value, the outstanding loan balance and the cost of selling the property.

Keep the home

An heir may choose to keep the property, but the reverse mortgage must first be satisfied.

This may be accomplished by:

  • Paying the balance with cash
  • Using other assets from the estate
  • Refinancing the balance into a traditional mortgage

With an FHA-insured Home Equity Conversion Mortgage, commonly called a HECM, special rules apply if the loan balance is higher than the home’s appraised value. In that situation, an heir who wants to keep the home may generally satisfy the debt by paying 95% of the appraised value rather than the full loan balance.

An heir who wants to keep the property should speak with the servicer early in the process. Refinancing and estate administration can take time.

Allow the lender to recover the property

A HECM is a nonrecourse loan. This means the lender generally looks to the property for repayment, not to the borrower’s heirs or their personal assets.

If the loan balance is greater than the home’s value and the family does not want to keep the property, the heirs may decide not to repay the loan. Depending on the circumstances, the estate may complete a deed in lieu of foreclosure or allow the lender to proceed with foreclosure.

The heirs generally are not personally responsible for paying the shortage between the home’s value and the loan balance.

How Much Time Do Heirs Have?

The loan servicer will provide the estate with information about the amount owed and the available options. The exact timeline may vary depending on the loan, the estate and what the heirs intend to do.

Extensions may be available when the heirs are actively working to sell the home or obtain financing, but they are not automatic. The estate may need to provide documentation showing that progress is being made.

For that reason, the heirs or the estate’s representative should contact the servicer as soon as possible after the borrower’s death. Waiting can limit the available options and make an already emotional process more difficult.

Will There Be Equity Left for the Heirs?

There may be. A reverse mortgage does not automatically consume all of the home’s equity.

The amount remaining for the estate depends on factors such as:

  • The home’s value when it is sold
  • The outstanding reverse mortgage balance
  • How much the borrower withdrew
  • How long the loan was in place
  • Interest and mortgage insurance charges added to the balance
  • Changes in the home’s value
  • Real estate and closing costs

Some homeowners use only part of their available reverse mortgage proceeds. Others may have the loan for many years. Because every situation is different, families should review the most recent loan statement and obtain a current estimate of the home’s value before making a decision.

Can a Borrower Lose the Home?

Having a reverse mortgage does not, by itself, cause the homeowner to lose the property. The borrower remains the owner and stays on the title.

However, the borrower must continue to meet the loan requirements. These typically include:

  • Occupying the home as a primary residence
  • Paying property taxes
  • Maintaining homeowners insurance
  • Keeping the property in reasonable condition
  • Paying applicable homeowners association fees

Failing to meet these obligations may cause the loan to become due and could eventually lead to foreclosure.

Planning Ahead Can Make the Process Easier

Families often do not discuss the reverse mortgage until the borrower has died or can no longer manage their finances. By that point, locating documents and deciding what to do with the home can feel overwhelming.

A few simple planning steps can make a meaningful difference:

  • Tell your family that you have a reverse mortgage.
  • Keep your loan documents and recent statements together.
  • Make sure a trusted family member knows the name of the loan servicer.
  • Discuss whether anyone may want to keep the home.
  • Keep property taxes, insurance and homeowners association payments current.
  • Review your estate plan with a qualified attorney.
  • Make sure the appropriate person has legal authority to communicate with the servicer when necessary.

These conversations may feel uncomfortable, but they can spare loved ones from having to make important decisions without enough information.

The Bottom Line

When a reverse mortgage borrower dies, the lender does not automatically become the owner of the home. The property remains part of the estate, and the heirs generally have the option to sell it, keep it by satisfying the loan, or allow the lender to recover it.

If equity remains after the reverse mortgage and selling expenses are paid, that equity belongs to the estate. If the loan balance exceeds the home’s value, the nonrecourse protection of an FHA-insured HECM generally prevents the borrower’s heirs from being personally responsible for the shortage.

The most important step is to communicate with the loan servicer promptly. Understanding the loan and discussing the family’s preferences in advance can make the process much easier when the time comes.

This article provides general information and is not legal, tax or financial advice. Loan requirements and estate laws may vary. Homeowners and heirs should consult the loan servicer and appropriate professional advisers regarding their circumstances.

What Are the Pros and Cons of Today’s Reverse Mortgage?

A reverse mortgage allows homeowners, typically aged 62 or older, to convert home equity into cash without selling their home or making monthly payments. Key pros include no obligatory mortgage payments, tax-free proceeds, optional flexible payment options, and protection against owing more than the home’s value. Main cons include significant upfront costs and increasing loan balance that can reduce home equity.

Key Pros:

  • No monthly mortgage payments: Borrowers can eliminate monthly payments, which can ease financial pressure and allow seniors to age in place.
  • Tax-free funds: Proceeds are generally not considered taxable income, and do not affect Social Security or Medicare benefits.
  • Flexible disbursement options: Borrowers can choose to receive funds as a lump sum, monthly payments, a line of credit, or a combination.
  • Non-recourse loan: Borrowers or heirs will never owe more than the home’s value when the loan is repaid, regardless of the loan balance.
  • Retain home ownership: Borrowers keep the title and can remain in their home, provided they fulfill obligations like property maintenance, taxes, and insurance.
  • Heirs have multiple options: When the homeowner leaves the home, heirs may repay the loan, sell the home and keep surplus equity, or, if the loan exceeds the home’s value, surrender the property with no further obligation.

Key Cons:

  • Accruing fees:  Reverse mortgages typically have higher closing costs, the most significant of which is the upfront FHA Mortgage Insurance Premium.
  • Decreasing home equity: If no payments are made, an absolute right of the homeowner, the loan balance grows over time, reducing the equity left for heirs or the homeowners if they sell and move.
  • Impact on inheritance: The growing loan balance can reduce the initial home value. 
  • Eligibility risks: As with all mortgages in the US, the homeowner must keep the home as their primary residence, maintain the property, and keep up with taxes and insurance.
  • Potential impact on means-tested benefits: While Social Security and Medicare are not affected, receiving large lump sums could impact eligibility for Medicaid or Supplemental Security Income (SSI). This subset of homeowners should take care to draw only what they need to spend for the month.

Clearly, the modern FHA-Insured reverse mortgage offers impressive benefits. The main drawbacks are related to cost, mostly the cost of insuring the loan. Many seniors find it reassuring that the loan is backed by the full faith and credit of the United States Government. Nevertheless, there are ways to reduce the overall cost of the reverse mortgage.

Key Methods for Reducing Overall Cost of Reverse Mortgages:

Payments on the reverse mortgage can be made or discontinued at any interval chosen by the homeowner

Paying the largest expense, the upfront MIP, instead of including it in the loan produces higher growth in available credit, and reduces the decline in home equity

Paying the largest expense, the upfront MIP as above, can result, for homeowners who itemize, in a tax reduction if the reverse mortgage is being used to purchase a new home or replace their purchase loan or to substantially renovate for a more desirable environment to age in place.

Making a large payment on an existing reverse mortgage in high-earning year to offset taxes

Taking draws from the reverse mortgage can be used in retirement planning :

Provide cash for living expenses while deferring Social Security

Meet irregular expenses such medical, aging home, or rising tax and insurance 

Self-insure for long-term care. Don’t use it, don’t owe it

Substitute reverse mortgage for portfolio draws in down markets, avoid buying high and selling low

Avoid paying capital gains by not selling to meet expenses

In high appreciation areas, retain the home for continued wealth building

Restrict capital gains for heirs by passing home on stepped-up basis

In senior divorce, equalize housing and reduce drain on marital cash

Over the last decade, there has been an explosion in retirement planning uses for reverse mortgages. Financial professionals appreciate how a usually dormant asset, the home, can be mobilized to work in concert with other assets.

Who Created Reverse Mortgages in the US?

Some people have heard that a reverse mortgage is a scheme or a scam perpetrated on helpless seniors. Others may consider a reverse mortgage a welfare handout.

Many are surprised to learn that the 100th U.S. Congress initiated the modern reverse mortgage through the Housing and Community Development Act of 1987, which President Ronald Reagan signed in February 1988.

Congress tasked the Federal Housing Administration (FHA) with designing a reverse mortgage that would protect older homeowners while also encouraging lending in the private sector.

In December 1988, the Department of Housing and Urban Development (HUD) published a notice asking potential mortgage lenders to participate in a demonstration program that would “insure up to 2,500 reverse mortgages on the homes of elderly homeowners, enabling them to turn their equity into cash.”

Through the Home Equity Conversion Mortgage (HECM) Insurance Demonstration, the modern reverse mortgage was born.

How FHA Insurance Works

The FHA addressed the need to protect both the homeowner and the lender by modifying its existing mortgage insurance program to accommodate reverse mortgage lending. Understanding how the FHA operates in traditional lending provides a helpful comparison.

Created in 1934 as part of the National Housing Act, the FHA provides mortgage insurance on loans made by FHA-approved lenders throughout the United States and its territories. The FHA insures mortgages on single-family and multifamily homes, including manufactured homes and hospitals. In 1965, the FHA became part of HUD.

At the height of the Great Depression, Congress and President Franklin Roosevelt created an incentive for lenders to provide financing to certain higher-risk borrowers by protecting lenders against loss. FHA insurance premiums were assessed on these loans and used to fund that protection.

With traditional FHA loans, homeowners pay upfront and monthly insurance premiums. These premiums protect lenders against losses if a homeowner defaults. FHA lenders bear less risk because the FHA may pay a claim to the lender following a homeowner’s default.

To qualify for FHA insurance protection, loans must meet specific requirements established by the FHA.¹

Adapting FHA Insurance to Reverse Mortgages

Insurance is based on the participation of many people to cover the losses of a few. In other words, participants pool funds by paying premiums, transferring a portion of the risk to the insurance provider.

The HECM program adopted the FHA insurance concept but modified it to accommodate the needs of reverse mortgage lending:

Insurance premiums are not paid monthly. Instead, they are added to the loan balance.

The homeowner or the homeowner’s estate is released from liability if the loan balance exceeds the home’s value.

If the home’s value does not cover the loan balance, the lender is protected by FHA insurance.

The resulting HECM program, which includes FHA insurance, is designed to encourage lenders to provide loan proceeds while protecting them if circumstances do not unfold as anticipated.

The HECM also protects homeowners and their estates if the loan balance grows beyond the value of the home. Its consumer safeguards are substantial and have continued to evolve to protect both individual borrowers and taxpayers.

Unfortunately, these HECM consumer protections are sometimes overlooked by the financial press and by financial advisers upon whom many Americans rely for information about their retirement options.

Addressing Weaknesses in the Program

Despite HUD’s continued efforts to refine the program, weaknesses emerged over time.

During the housing bubble years, HECMs were sometimes used to address financial situations that were already unsustainable. Some borrowers did not take seriously the requirement to remain current on their property taxes and homeowners insurance.

In other cases, younger spouses who were not listed on the property title were displaced when the borrower died. Some borrowers also used the HECM irresponsibly by withdrawing their entire initial credit limit at closing, leaving no cushion if home values declined.

These were serious problems that jeopardized both the program and its reputation.

In response, the 113th Congress passed the Reverse Mortgage Stabilization Act of 2013. The law was enacted to provide additional protections for non-borrowing spouses and to help restore the financial health of the FHA Mutual Mortgage Insurance Fund.

The HECM program’s insurance pool was intended to be self-sustaining, not a taxpayer bailout. However, when the housing bubble collapsed, the fund’s solvency was placed in jeopardy. HUD responded by changing its lending standards, and the HECM program was significantly revised. As a result, the fund’s financial strength began to improve.²

Additional Consumer Protections

Financial assessments are now part of the HECM loan approval process.

To reduce the likelihood of property tax and homeowners insurance defaults, formulas are used to determine whether a portion of the borrower’s available equity must be set aside to cover these expenses. These set-asides may be required when borrowers cannot demonstrate the willingness or financial capacity to meet their basic housing obligations.

Additional protections include:

Limits on how much equity borrowers can access during the early stages of the loan

Financial assessments designed to determine whether borrowers can meet their ongoing housing obligations

Set-asides for property taxes and homeowners insurance when required

Non-borrowing spouse provisions that may allow an eligible younger spouse who is not old enough to borrow to remain in the home after the borrowing spouse dies

A Program That Continues to Evolve

Rather than being a fraudulent scheme designed to take advantage of older homeowners, the modern reverse mortgage, also known as the HECM, is a program established by the United States government.

As former FHA Commissioner Brian Montgomery has said, the HECM is the “law of the land.”

Admittedly, the HECM program was not perfect at its inception. Like many financial products, however, it has evolved. HUD continues to refine the program to strengthen consumer protections and improve risk management for the FHA insurance fund.

A reverse mortgage is neither inherently good nor bad. Its value depends on how the borrower uses it.

Notes

Information about FHA program requirements and history is available through the U.S. Department of Housing and Urban Development.

The original article cited an archived Reverse Review resource concerning the HECM program and the FHA Mutual Mortgage Insurance Fund.

How Would More Attention to the Housing Asset Affect the Covid-19 Retirement?

FPA San Francisco Newsletter

Rick San Vicente, VP NW Sales Leader, Mutual of Omaha Mortgage

with

Shelley Giordano, Academy of Home Equity in Financial Planning, University of Illinois

The famous physicist Werner Heisenberg reportedly mused that when he gets to Heaven, he hopes that “turbulence” can be at last be explained to him. Tongue-in-cheek, Heisenberg claimed that even the theory of relativity would be easier to grasp than the tendency of things to change in unpredictable ways. For retirees in midst of the Covid-19, the volatility in investments, especially in March 2020, was a reminder that retirement planning is fraught with the need to make assumptions that may or may not provide for a secure future.

Wade Pfau, PhD, CFA, Professor of Retirement Income at the American College of Financial Services, writes that market turbulence, longevity, and spending shocks are the three major threats to financial security in retirement.  To mitigate these risks, Dr. Pfau recommends that the advisor integrate the housing asset into the planning process. Dr. Pfau’s approach is to treat the home as a “buffer asset” that may be deployed to protect the investments should the client live long, encounter unexpected expenses, or even temporarily need an alternative source of cash to avoid selling in a bear market.

With an estimated $7 trillion in senior home equity, would turning this dead asset into a integrated strategy for your clients help restore peace of mind, especially in view of the economic and health consequences that retirement in the Covid-19 world may bring?

The most dramatic use of the reverse mortgage, and the most popular, is to convert a traditional mortgage into a reverse. This immediately removes the dreaded monthly mortgage payment and gives clients breathing room to enjoy life. 

Retirees are often surprised that dental, vision aid, and hearing aid are not only not covered by Medicare but also that they are so expensive. Possible long-term care needs just add to the uncertainty of what the future will cost.

And finally, clients are anxious about their investments lasting as long as they do. Having to take distributions in a down market is unsettling enough that even Congress in the 2020 CARES ACT suspended RMDs.  Selling in down markets is known as “Sequence of Returns Risk. “Clients just know it as buying high and selling low. 

A reverse mortgage line of credit can be used as substitute draws while the market recovers. The modern reverse mortgage, or Home Equity Conversion Mortgage (HECM), is FHA-insured and provides for growing access to borrowing power as the client ages. Although the HECM line of credit is similar to a home equity line of credit, there are critical differences. When there is turbulence in the financial markets, lenders can substantially alter their commitment to lend on home equity. This was a painful lesson in the Great Recession. Just when clients needed liquidity, the banks did, too, and stopped lending. Already we have seen Chase and Wells Fargo suspend HELOCs during the Covid-19 pandemic. 

But clients who have a reverse mortgage line of credit cannot be denied access to their growing line. As opposed to a HELOC, the HECM line of credit cannot be

Cancelled

Frozen

Reduced


Substituting draws from invested funds with draws on a reverse mortgage puts the house to work in a particularly effective way. To prepare for the unexpected, the house is an important part of the retirement planning process.

Long-Term Care: Bridging the Gap

Few financial threats are more destructive to a retirement plan than a prolonged long-term care event. Medicare covers custodial care for only a short time, leaving families to face difficult choices: spend down assets to qualify for Medicaid, or pay out of pocket — bills that can easily climb into the hundreds of thousands of dollars. One often-overlooked solution is establishing a reverse mortgage Home Equity Conversion Mortgage (HECM) Line of Credit early in retirement, creating a growing financial reserve that exists outside of traditional savings.

Even when long-term care insurance is in place, gaps remain. According to the American Academy of Long-Term Care Insurance (AALTCI), only about half of policyholders ever file a claim. And for those who do, coverage doesn’t begin immediately — most policies include an elimination period, typically 90 days, during which the policyholder pays out of pocket before benefits kick in. Factor in that some people recover or pass away during that waiting period, and the likelihood of actually using the policy drops to around 35%. Beyond the elimination period, daily benefit amounts often fall short of actual care costs, leaving families to cover the difference.

Consider Sharon and Bob, a Massachusetts couple who found themselves in exactly this situation. When Bob needed care, they discovered their policy’s 90-day elimination period would cost roughly $30,000 — far more than they had anticipated when they purchased coverage years earlier. On top of that, the policy’s daily benefit wouldn’t fully cover Bob’s actual care costs, creating an ongoing shortfall Sharon wasn’t sure how to manage. With just $500,000 in savings and Social Security income, she was understandably reluctant to drain their nest egg.

Their solution was a HECM Line of Credit on their home. An initial draw of $50,000 covered the elimination period and helped pay down some existing debt, such as Sharon’s car. The remaining $350,000 credit line now bridges the gap between what Bob’s care costs and what the insurance pays each day. Because no monthly payments are required on the borrowed funds, their cash flow remains stable — and their retirement savings stay invested, continuing to grow for the future.